The Finance Director who needed a number, not a dream
A month ago, a 45-year-old woman who works as a Finance Director at an MNC reached out to Finamily. She had a 10-year-old kid she was raising alone.
She had meaningful PF accumulated over years. Some investments: a mix of ULIPs and mutual funds built up earlier.
She came with a question she couldn't answer with the information she had:
"When would be the right time to leave my job?"
She had been building other interests and was genuinely keen to pursue. But her interest was not yet self-sustaining from a business point of view.
She wanted to know how soon she could retire and pursue her interest. Her hope was 1 to 2 years.
She came to Finamily not for validation but for clarity.
The situation: ambition without a framework
The client had no shortage of motivation or intelligence; she was a finance director, after all. What she lacked was a structured map of her own financial reality.
Her existing investments were scattered. She had ULIPs with suboptimal return potential. She also had mutual funds started at various points without a unifying goal. A substantial PF balance she hadn't modelled into a retirement plan.
No clear calculation of what her daughter's education or marriage would cost, when those costs would arrive, or how much she needed invested today to meet them.
She had assets. She didn't have clarity on her plan.
And without clarity, her question as to when she can retire had no honest answer
What we did: Three goals, three timelines, one clear picture
The first thing we did was not touch a single investment. We mapped the future.
Every upcoming expense was identified, named, and sized. Then we worked backwards from each one.
Goal 1: Daughter's undergraduate education (8 years away)
We estimated how much the child’s education would cost in 8 years down the line, applied a realistic education inflation rate, and calculated backwards: how much needs to be invested today, and in what mix of equity and debt, to meet this number comfortably.
Goal 2: Daughter's marriage (approximately 18 years away)
Same exercise. Longer horizon. Higher equity allocation appropriate. Specific corpus target derived. Current investment gap identified.
Goal 3: Retirement (the central question)
Here we used everything already in place as inputs: the PF balance, the existing mutual funds, the ULIPs, and modelled their projected value at different retirement dates. We also factored in her monthly expenses today, an inflation rate, and a retirement duration.
The output was a specific number: the corpus she needed to retire with confidence, and the date at which her current savings trajectory would reach it.
The Finamily solution: hard truth, real relief
The number was honest. And the number said: not 1 to 2 years.
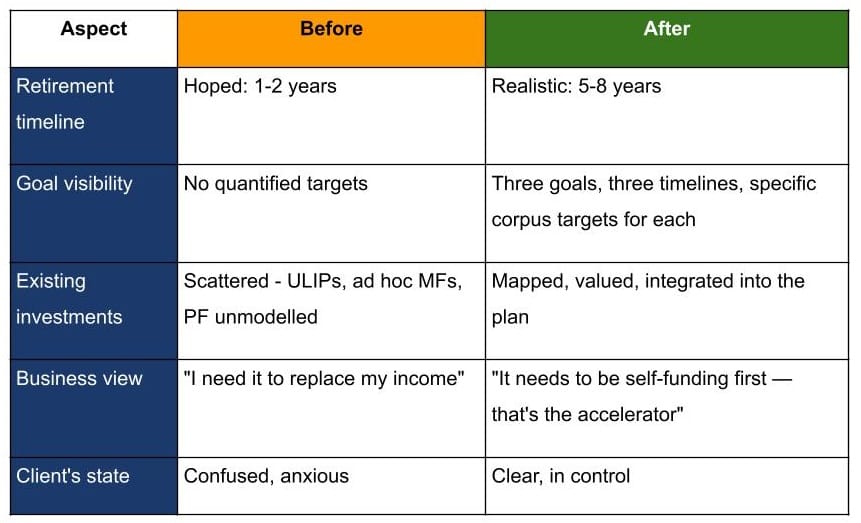
The realistic retirement window, on her current trajectory: 5 to 8 years.
This was not what she had hoped to hear. But here is what happened when she heard it:
She was relieved.
Not because the timeline was comfortable. She could see the specific levers that would change the outcome.
We also reframed something important about her parallel business: if that venture became self-funding from the start, covering its own costs without drawing from her savings, her path to retirement would accelerate significantly. The business didn't need to replace her income immediately. It needed to stop being a drain. That was a meaningful and achievable near-term target.
The before and after wasn't a dramatic portfolio transformation. It was a clarity transformation.
"The most important thing I wanted was clarity. I was confused. I don't mind working for 5 or 8 more years; I just needed to make sure I really understand and get a grip and control over my finances. At Finamily, I was able to do that."
What this case study is really about
This client did not come to me with a broken portfolio. She came with a broken picture.
My job was not to find her a magic fund that would make everything work in 2 years. It was to give her an honest, quantified picture of her reality, and a systematic path forward that she could trust.
The most important outcome from this engagement was not a number. It was a person who went from confused to in control.
If you have a life transition on the horizon - a career shift, early retirement, a business you want to build - and you're working with hope rather than a plan, this conversation is where to start.
VBA STATE OF PLAY - SEPTEMBER 2026
The framework compares current valuations (P/E ratios) against long-term historical medians to identify where value and margin of safety reside.
To know more about what is the VBA Framework→ Read the full explainer here
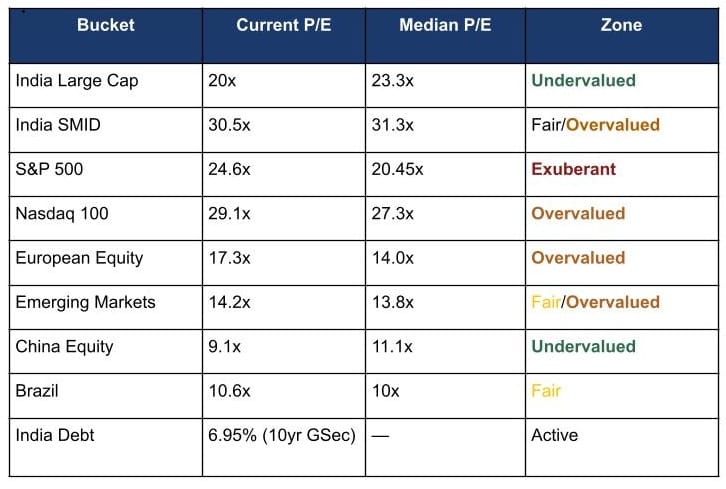
Allocation Flow — Where fresh capital goes this month
China (Undervalued) → Brazil (Fair — satellite, time-sensitive)→India Large Cap (Fair — one index fund) → Emerging Markets (Fair) → India Debt (Short Duration — goal-based) → Hold: S&P 500 / Nasdaq/India SMID
Note: The VBA Framework allocates based on current valuations. It does not predict where markets are going. This newsletter is for educational purposes only and does not constitute investment advice. Mutual fund and equity investments are subject to market risks.
FUND BREAKDOWN
ICICI Prudential Technology Fund
India's oldest technology fund and the one that's earned the right to be called battle-tested. Know more>
References
ICICI Prudential Technology Fund fact sheets; World PE ratio, Screener, Groww, MSCI. Figures were pulled from public sources across July–August 2026. Always cross-check against the current factsheet before acting on anything here.
Published for educational purposes only. This is not investment advice, not a research report under SEBI's RA regulations, and contains no buy/sell/hold recommendation. These are insights on a publicly available mutual fund, meant to help readers to understand the fund relevance to their portfolio. Data as of August 28, 2026 unless dated otherwise, always verify against the latest factsheet before relying on any number here.
This is not a buy or sell recommendation. This newsletter is for educational and informational purposes only. Investing in single-country emerging market funds carries significant risk, including the risk of substantial capital loss. Please read all scheme-related documents carefully. Past performance is not indicative of future returns. The VBA Framework allocates based on current valuations and does not predict market direction.
JOIN MY NEWSLETTER
Hi! I'm Avinash
Welcome to my blog. This is a collection of real case studies from my clients that helps you understand how to solve investment problems and approach financial goals.
Created with © Avinash Baskar | AMFI-registered Mutual Fund Distributor ARN-264201